
Why Banks Freeze Accounts: 7 Reasons You Didn’t See Coming
Discover the 7 hidden reasons banks freeze accounts—from AML alerts to dormant‑account rules—and learn how to protect your money.
Keywords: bank account freeze reasons, why banks freeze accounts, account freeze explained
Hashtags: #Banking #AccountFreeze #FinancialTips
📌 Overview
| What you’ll learn | Why it matters | How to use it |
| The 7 most common (and surprising) triggers that cause a bank to lock your account | Prevent costly disruptions, fees, and credit damage | Spot red flags early, respond quickly, and keep your finances flowing |
Introduction
Imagine logging into your online banking portal, ready to pay a bill, only to see a stark, red‑lined message: “Your account has been frozen.” Your heart skips a beat. You didn’t miss a payment, you haven’t taken out a loan, and you certainly didn’t receive any warning.
Account freezes are more than an inconvenience—they can halt payroll, stall emergency purchases, and even damage your credit if left unresolved. While many people assume a freeze only follows obvious fraud or a court order, banks operate under a complex web of regulatory, legal, and operational rules that can trigger a lockout without any obvious warning.
In this long‑form guide (≈ 2,300 words), we’ll peel back the curtain on the seven reasons you probably didn’t see coming when a bank decides to freeze your account. We’ll explain the legal backdrop, the red‑flag behaviors that set off alarms, and—most importantly—what you can do right now to protect yourself and quickly restore access.
Whether you’re a small‑business owner, a freelancer juggling multiple accounts, or just a consumer who wants peace of mind, understanding these triggers equips you to spot trouble before it freezes your cash flow.
Table of Contents
- Regulatory Red Flags: Anti‑Money‑Laundering (AML) & Terrorist Financing Alerts
- Court Orders, Judgments & Garnishments
- Tax‑Related Holds (IRS, CRA, etc.)
- Negative Balances, Overdrafts & Unpaid Fees
- Identity & Verification Failures (KYC “Know‑Your‑Customer” Gaps)
- Sanctions & Regulatory Compliance (OFAC, EU, etc.)
- Dormancy, Inactivity & “Dead” Accounts
- Quick‑Action Checklist: How to Unfreeze Your Account
- Preventive Best Practices (Stay One Step Ahead)
- [Final Thoughts]
- Regulatory Red Flags: Anti‑Money‑Laundering (AML) & Terrorist Financing Alerts
What the law says
Financial institutions in the U.S., Canada, EU, and most jurisdictions are bound by AML statutes (e.g., the USA PATRIOT Act, Canada’s Proceeds of Crime (Money Laundering) and Terrorist Financing Act). Banks must monitor every transaction for patterns that could indicate money‑laundering, structuring, or illicit financing.
How a freeze is triggered
- Unusual transaction volume – A sudden surge of deposits or withdrawals that far exceeds typical activity.
- Geographic red flags – Funds moving to/from high‑risk jurisdictions (e.g., Iran, North Korea).
- Structuring (“smurfing”) – Multiple small deposits just under reporting thresholds ($10,000 in the U.S.).
- Rapid turnover – Money deposited and withdrawn within minutes, especially via online wallets.
When the bank’s AML software flags a transaction, a compliance officer reviews the activity. If they can’t verify the source or purpose, they may freeze the account pending investigation to avoid regulatory penalties.
Real‑world example
A freelance graphic designer started receiving $30k‑plus payments from a new overseas client. Within a week, the bank’s AML system generated an alert for “high‑risk international transfers.” The account was frozen for 48 hours while the bank requested proof of the contract and invoices.
What you can do
- Maintain documentation for all sizable or international transfers (contracts, invoices, receipts).
- Notify your bank in advance of expected large deposits—especially if they’re out of the ordinary for your account profile.
- Use a single, consistent source of income where possible; frequent changes raise suspicion.
- Court Orders, Judgments & Garnishments
The legal backbone
When a court issues a judgment, lien, or garnishment, it can command a bank to freeze the debtor’s account to satisfy the debt. This includes:
- Civil judgments (unpaid loans, personal injury settlements)
- Child support or alimony orders
- Tax liens (see Section 3)
- Bankruptcy stays
Banks receive a writ of garnishment or notice of levy and must comply within a statutory window (often 10–30 days), or they risk contempt of court.
Why you might not expect it
- Third‑party debt – A creditor may obtain a judgment against you without your knowledge (e.g., a medical provider).
- Joint accounts – A judgment against a co‑owner can affect the entire account, even if you’re not the primary debtor.
- Hidden liens – Some liens are filed at the county level and may not appear on a standard credit report.
Real‑world example
A couple shared a checking account. One spouse was sued for a personal injury claim and a $75,000 judgment was entered. The creditor served the bank with a garnishment order, freezing the entire joint account. The other spouse, unaware of the lawsuit, suddenly couldn’t access their paycheck.
What you can do
- Monitor public records (county clerk, state court websites) for any filings under your name.
- Ask your attorney to request a notice of intent to levy before a freeze occurs (some jurisdictions require a 10‑day notice).
- Separate finances: Keep personal and business accounts distinct, and consider a trust or LLC for high‑risk assets.
- Tax‑Related Holds (IRS, CRA, HMRC, etc.)
Why tax agencies freeze accounts
Tax authorities have the power to levy a taxpayer’s bank account to collect unpaid taxes. In the U.S., the IRS uses Notice of Federal Tax Lien (NFTL) and Final Notice of Intent to Levy before freezing. Canada’s CRA issues a Requirement to Pay (RTP) and a Letter of Requirement.
Unexpected triggers
- Unfiled returns – Even if you owe nothing, failing to file can lead to a freeze.
- Incorrect address – Notices sent to an old address may never reach you, leaving you unaware of an impending levy.
- Business vs. personal confusion – Tax debt tied to a business entity can spill over into a personal account if the bank cannot separate the funds.
Real‑world example
A freelance photographer filed a 2022 return late, owing $4,500. The IRS sent a levy notice to his bank, but it was mailed to his previous apartment. Two weeks later, his account was frozen, and he missed a mortgage payment.
What you can do
- Enroll in direct‑deposit for refunds and e‑file to get immediate confirmation of filing.
- Update contact information with the tax agency promptly after any move.
- Respond to any “Notice of Intent to Levy” within the 30‑day window—often a payment plan can be arranged to avoid a freeze.
- Negative Balances, Overdrafts & Unpaid Fees
The obvious but often overlooked cause
When an account goes deep into the red (overdraft) and the bank cannot recover the debt, they may freeze the account to prevent further loss. This can also happen when:
- Monthly service fees are unpaid for several cycles.
- Returned checks (NSF) accumulate, leading to a “reversal” hold.
Why it can happen without warning
- Automatic overdraft protection may be turned off without the customer’s knowledge.
- Online banking alerts may be missed if you haven’t set up push notifications.
- Bank policy changes—some institutions have tightened overdraft limits after regulatory pressure.
Real‑world example
A small‑business owner relied on a “soft” overdraft line that the bank discontinued overnight. A $2,300 purchase pushed the balance to –$1,800. The next day, the bank placed a hold, freezing all outgoing transactions until the balance was covered.
What you can do
- Set up low‑balance alerts (SMS or email).
- Maintain a buffer of at least one month’s average expenses.
- Negotiate a payment plan with the bank as soon as you see a negative balance—most will lift the freeze once a repayment schedule is in place.
- Identity & Verification Failures (KYC “Know‑Your‑Customer” Gaps)
The regulatory driver
Banks must verify the identity of every customer under KYC rules (e.g., the USA PATRIOT Act, EU’s 5AMLD). If a customer’s documents are expired, inconsistent, or missing, the bank may freeze the account until compliance is restored.
Surprising triggers
- Name changes (marriage, divorce) not updated in the bank’s system.
- New address without supporting proof (utility bill, lease).
- Multiple ID types (passport vs. driver’s license) causing mismatched data.
- Social Security Number (SSN) discrepancies flagged by the bank’s fraud engine.
Real‑world example
A recent graduate moved from a dorm to an apartment and updated her address online but didn’t upload a new utility bill. The bank’s KYC system flagged the mismatch, froze the account, and prevented her from receiving her first paycheck.
What you can do
- Upload documents promptly when you receive a KYC request.
- Use the same name and address across all financial institutions.
- Keep a digital copy of your ID, proof of address, and SSN card for quick upload.
- Sanctions & Regulatory Compliance (OFAC, EU, UN)
Why sanctions matter
Governments maintain sanctions lists (e.g., the U.S. Office of Foreign Assets Control—OFAC). If a customer, or a transaction counterpart, appears on a sanctions list, banks must freeze the account or transaction to avoid violating the law.
Hidden ways a freeze can happen
- Beneficiary of a payment is on a sanctions list, even if you didn’t know.
- Family member shares a name with a sanctioned individual, triggering a false positive.
- Cryptocurrency conversion—many banks now monitor crypto‑related activity for sanctions exposure.
Real‑world example
An entrepreneur received a payment from a supplier in a country under U.S. sanctions (Iran). The bank’s automated screening flagged the inbound wire, froze the account, and required proof that the funds were not linked to a prohibited entity. The freeze lasted 10 days, delaying a critical product launch.
What you can do
- Screen your vendors and customers using publicly available sanctions lists before initiating large transfers.
- Ask the bank for a “pre‑clearance” on high‑risk transactions.
- Maintain a clear audit trail (invoices, contracts, shipping documents) to demonstrate legitimate business purpose.
- Dormancy, Inactivity & “Dead” Accounts
The rule of thumb
Most banks label an account “dormant” after 12–24 months of no activity (no deposits, withdrawals, or login). Regulations (e.g., ESIGN Act, State Unclaimed Property Laws) require banks to freeze or escheat dormant accounts after a set period.
Unexpected triggers
- Seasonal accounts—e.g., a vacation‑home savings account used only once a year.
- Automatic payment failures—if a recurring bill fails because of insufficient funds, the account may be considered inactive.
- Digital‑only banks—some fintechs have stricter inactivity policies (30 days) to mitigate fraud.
Real‑world example
A retiree kept a small savings account for occasional medical expenses, depositing once a year. After 18 months of inactivity, the bank placed a hold and sent a notice to the last known address. The retiree didn’t receive it, and the account was eventually transferred to the state’s unclaimed property division.
What you can do
- Schedule a recurring small deposit (e.g., $1) every quarter.
- Set up a monthly login reminder to keep the account “alive.”
- Update your mailing address with the bank whenever you move.
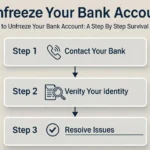
Quick‑Action Checklist: How to Unfreeze Your Account
| Step | What to Do | Typical Timeline |
| 1️⃣ Identify the reason | Review the bank’s notification (email, letter, portal message). | Immediate |
| 2️⃣ Gather documentation | Contracts, court orders, tax notices, ID copies, proof of source of funds. | 1–3 days |
| 3️⃣ Contact the right department | Compliance, legal, or collections—use the phone number on the notice. | Same day |
| 4️⃣ Submit a formal request | Written request (email or fax) with attached docs; keep a copy. | 1 day |
| 5️⃣ Follow up | Call every 48 hours if you don’t receive a response. | Ongoing |
| 6️⃣ Confirm resolution | Ask for a written confirmation that the freeze is lifted. | Within 7–14 days (varies) |
| 7️⃣ Implement safeguards | Set alerts, change passwords, adjust account usage. | Ongoing |
Pro tip: Most banks will lift a freeze within 5–10 business days once they verify the required information. The key is prompt, organized communication.
Preventive Best Practices (Stay One Step Ahead)
- Maintain a “Document Vault” – Store contracts, tax notices, and identity proofs in a secure cloud folder (e.g., encrypted Google Drive).
- Set Up Multi‑Channel Alerts – SMS, email, and push notifications for low balances, large transactions, and login attempts.
- Annual KYC Refresh – Proactively update your ID and address each year, even if the bank doesn’t ask.
- Separate High‑Risk Funds – Use a dedicated account for international or crypto‑related transactions.
- Regularly Review Public Records – A quick quarterly search for judgments or liens can catch problems early.
- Know Your Bank’s Policies – Read the “Account Maintenance” section of your agreement; some banks disclose dormancy periods and freeze triggers.
- Establish a Backup Funding Source – Keep a secondary checking account (or a credit line) to cover essential payments if your primary account is frozen.
Final Thoughts
A bank‑initiated freeze can feel like an unexpected roadblock, but it’s rarely a mystery. Regulatory compliance, legal judgments, tax obligations, and simple operational oversights are the primary culprits. By understanding the seven hidden reasons outlined above, you can:
- Spot red flags early before they become full‑blown freezes.
- Respond quickly with the right documentation, minimizing downtime.
- Implement safeguards that keep your money liquid and your credit intact.
Remember: Proactive communication with your bank is your strongest defense. When you anticipate a large deposit, a change in address, or a legal development, give your bank a heads‑up. In most cases, a brief conversation can prevent a freeze altogether.
If you ever find yourself staring at that dreaded “Your account has been frozen” message, refer back to this guide, follow the checklist, and you’ll be back in control faster than you think.
Disclaimer
The information provided in this article is for general educational purposes only and does not constitute legal, tax, or financial advice. Regulations and banking policies vary by jurisdiction and may change over time. Always consult with a qualified attorney, tax professional, or financial advisor for advice tailored to your specific situation.
About MATRIXCORALS.COM
MATRIXCORALS.COM is a trusted digital hub offering clear, research‑backed content on personal finance, banking, and wealth‑building strategies. Our mission is to empower readers with actionable insights that demystify complex financial topics, helping them make confident decisions and protect their financial well‑being.
Ready to safeguard your accounts? Subscribe to MATRIXCORALS.COM for weekly updates, exclusive checklists, and expert Q&A sessions.




Leave a comment